Image Source: Google
Being a landlord comes with its unique set of risks and responsibilities. Landlord insurance is a crucial tool in protecting your investment property and yourself from potential financial losses. Understanding the key coverage options available to landlords is essential in making informed decisions about your insurance needs. In this guide, we will explore the key coverage options that every landlord should know.
1. Property Coverage
Property coverage is the foundation of any landlord insurance policy. This type of coverage protects your rental property from physical damage caused by covered perils such as fire, vandalism, or natural disasters. It typically covers the building itself as well as any personal property you own that is used to maintain the rental property.
Key points to know about property coverage:
- It protects against damage to the structure of the building, such as the roof, walls, and floors.
- It also covers personal property that you keep at the rental property, such as appliances or maintenance equipment.
- Check your policy for specific exclusions, such as damage caused by floods or earthquakes, as these may require additional coverage.
2. Liability Coverage
Liability coverage is another essential component of landlord insurance. This type of coverage protects you in case someone is injured on your rental property and holds you responsible for their medical expenses or legal fees. It also covers property damage caused by you or your tenants.
Key points to know about liability coverage:
- It provides financial protection in case of lawsuits related to injuries or property damage on your rental property.
- Most landlord insurance policies offer a minimum of $100,000 in liability coverage, but you may want to consider increasing this limit depending on your assets and risks.
- Liability coverage does not typically cover injuries to you or your family members living on the property; you may need a separate personal liability policy for that.
3. Loss of Rental Income Coverage
Loss of rental income coverage is designed to protect landlords from financial losses if their rental property becomes uninhabitable due to a covered peril. This coverage typically reimburses you for lost rental income while the property is being repaired or rebuilt.
Key points to know about loss of rental income coverage:
- It helps you maintain a steady income stream even if your rental property is temporarily out of commission.
- Some policies may also cover additional expenses incurred while the property is being repaired, such as hotel stays for displaced tenants.
- Make sure to check the specific limits and coverage periods of this type of coverage in your policy.
4. Umbrella Insurance
Umbrella insurance provides an extra layer of liability protection beyond the limits of your standard landlord insurance policy. It is designed to protect you from catastrophic events that could result in significant financial losses, such as a large lawsuit.
Key points to know about umbrella insurance:
- Umbrella insurance kicks in once the liability limits of your primary landlord insurance policy have been exhausted.
- It is relatively inexpensive compared to the additional coverage it provides, making it a cost-effective way to enhance your liability protection.
- Umbrella insurance can provide coverage for a wide range of liability risks, including libel, slander, and defamation claims.
5. Additional Coverage Options
In addition to the key coverage options mentioned above, there are several other types of coverage that landlords may want to consider adding to their insurance policy to tailor their coverage to their specific needs.
Some common additional coverage options include:
- Flood insurance: Protects against damage caused by floods, which are not typically covered by standard property insurance policies.
- Earthquake insurance: Covers damage caused by earthquakes, which are also usually excluded from standard property insurance.
- Vandalism insurance: Provides coverage for damage caused by vandalism to your rental property.
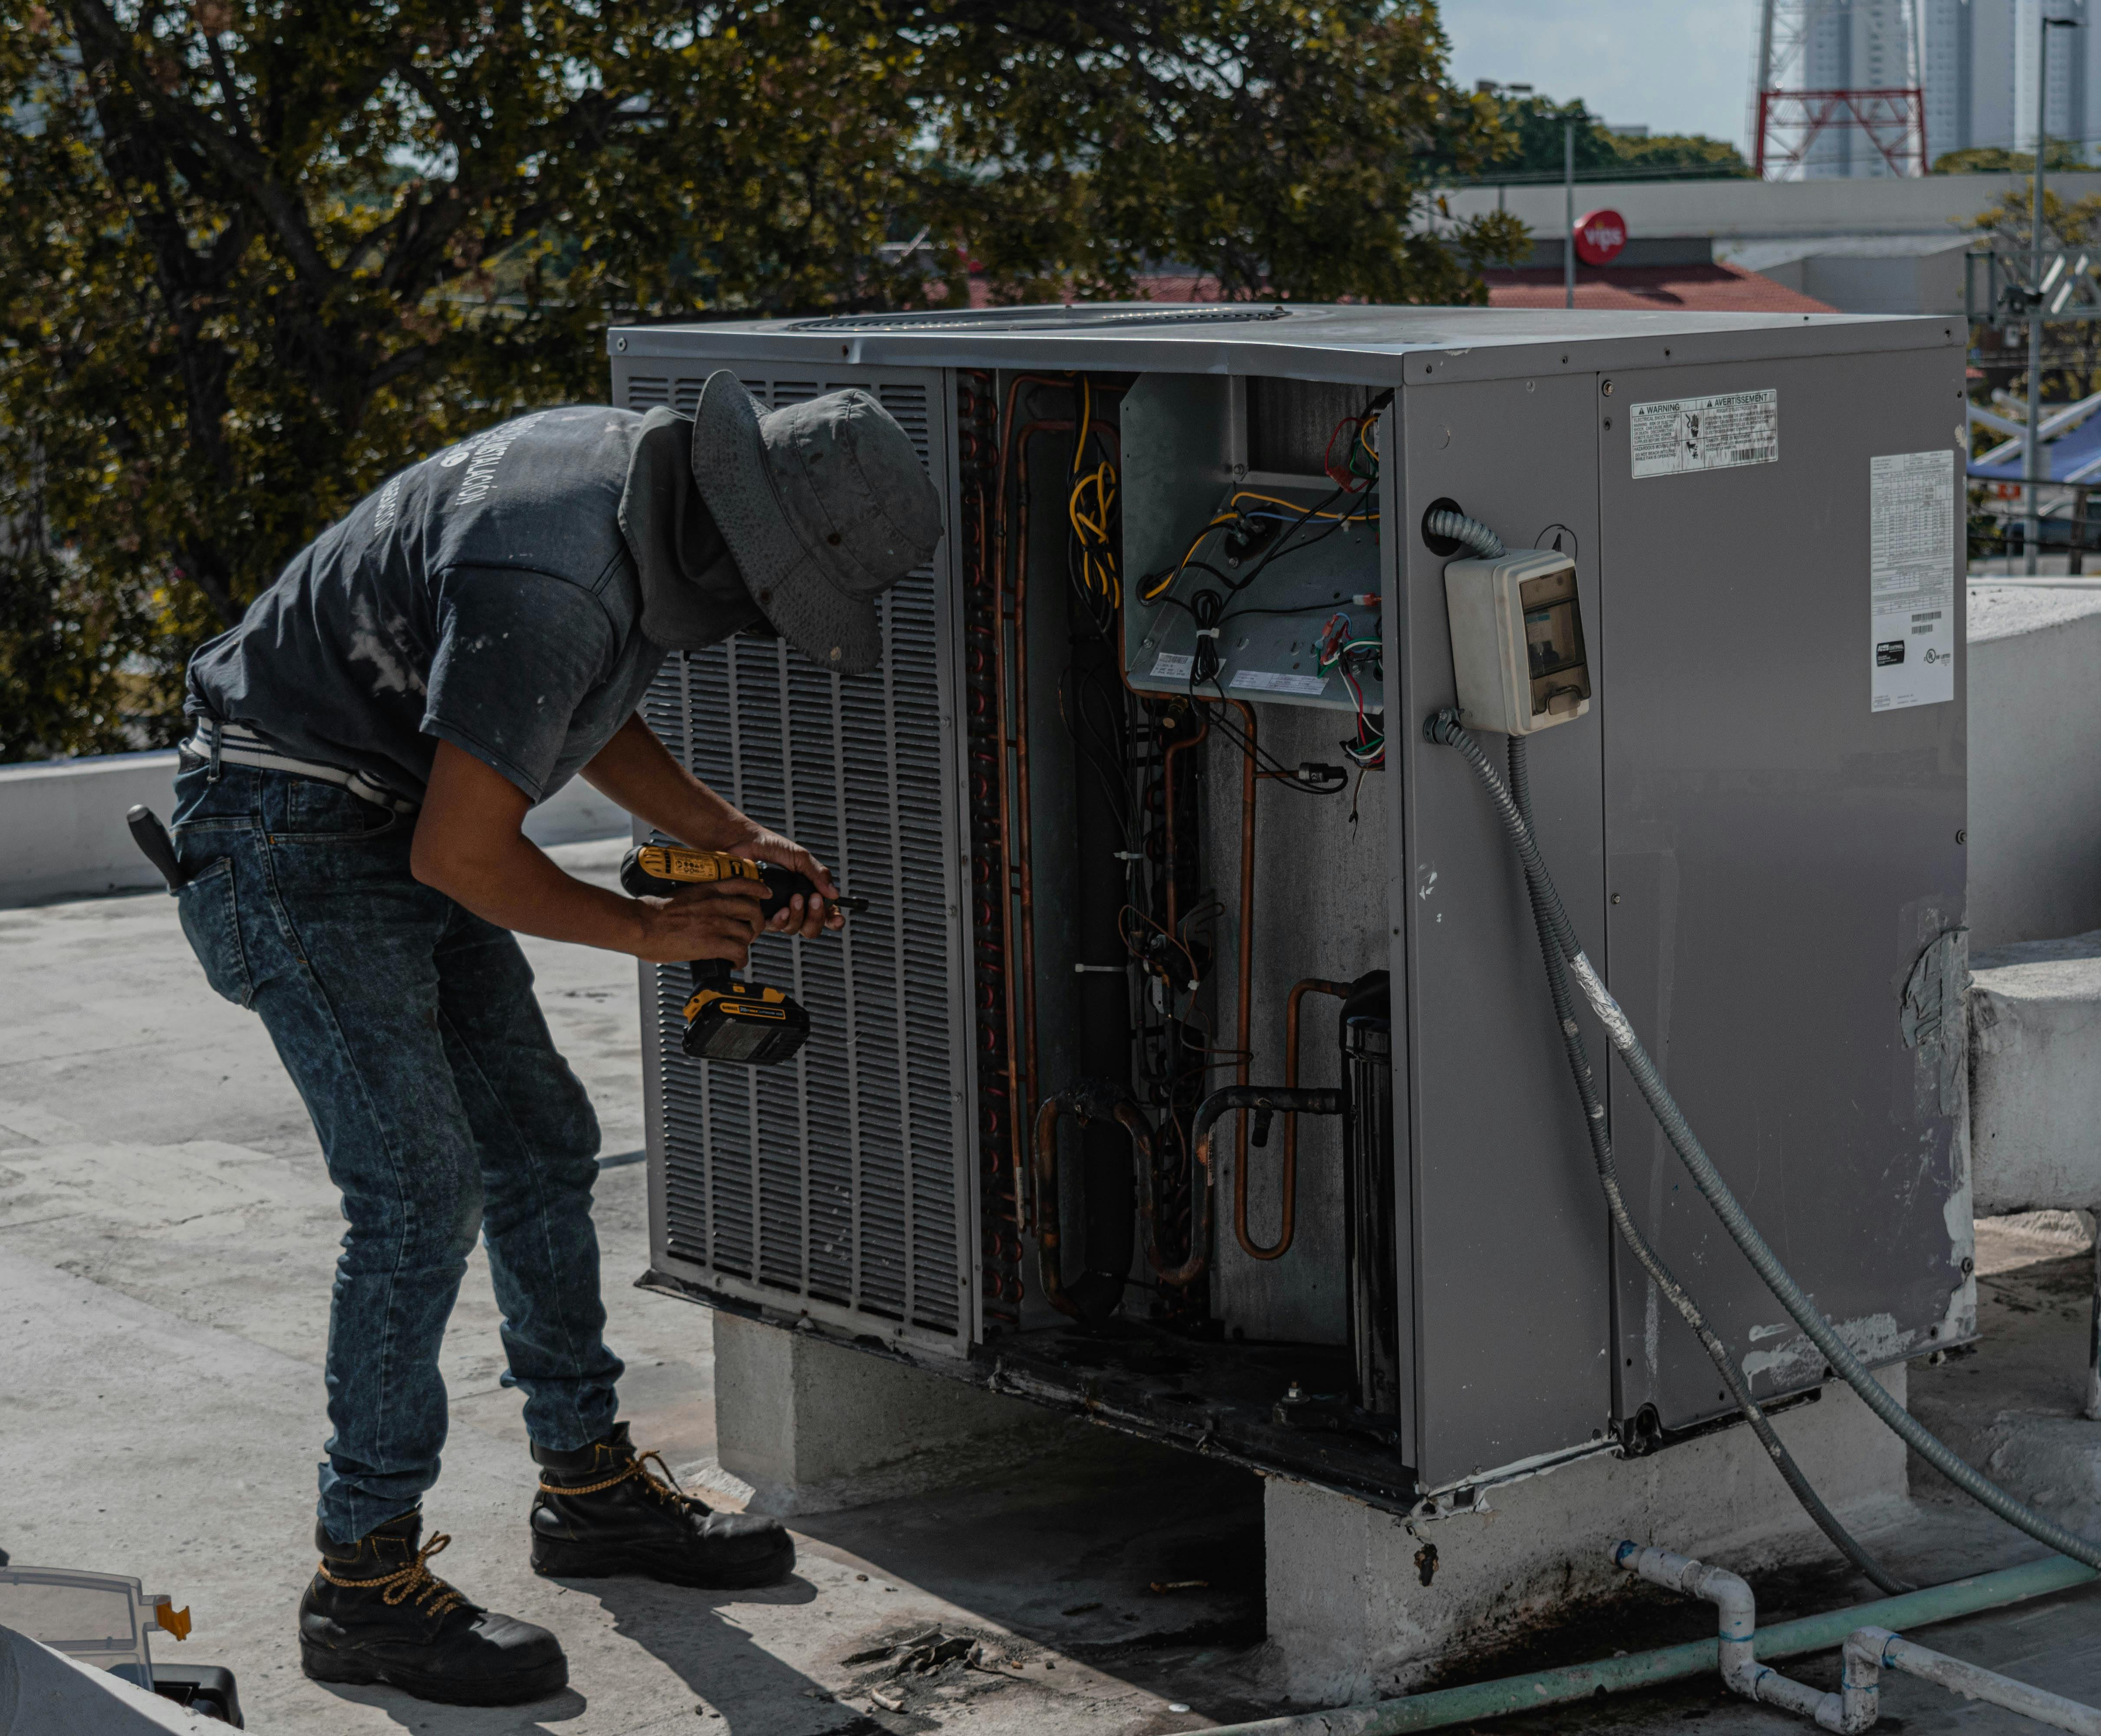
- Equipment breakdown coverage: Covers the cost of repairing or replacing essential equipment, such as furnaces or air conditioning units, in case of a mechanical breakdown.
By understanding these key coverage options and additional coverage options, landlords can make informed decisions about their insurance needs and ensure they have adequate protection in place to safeguard their investment property and finances.